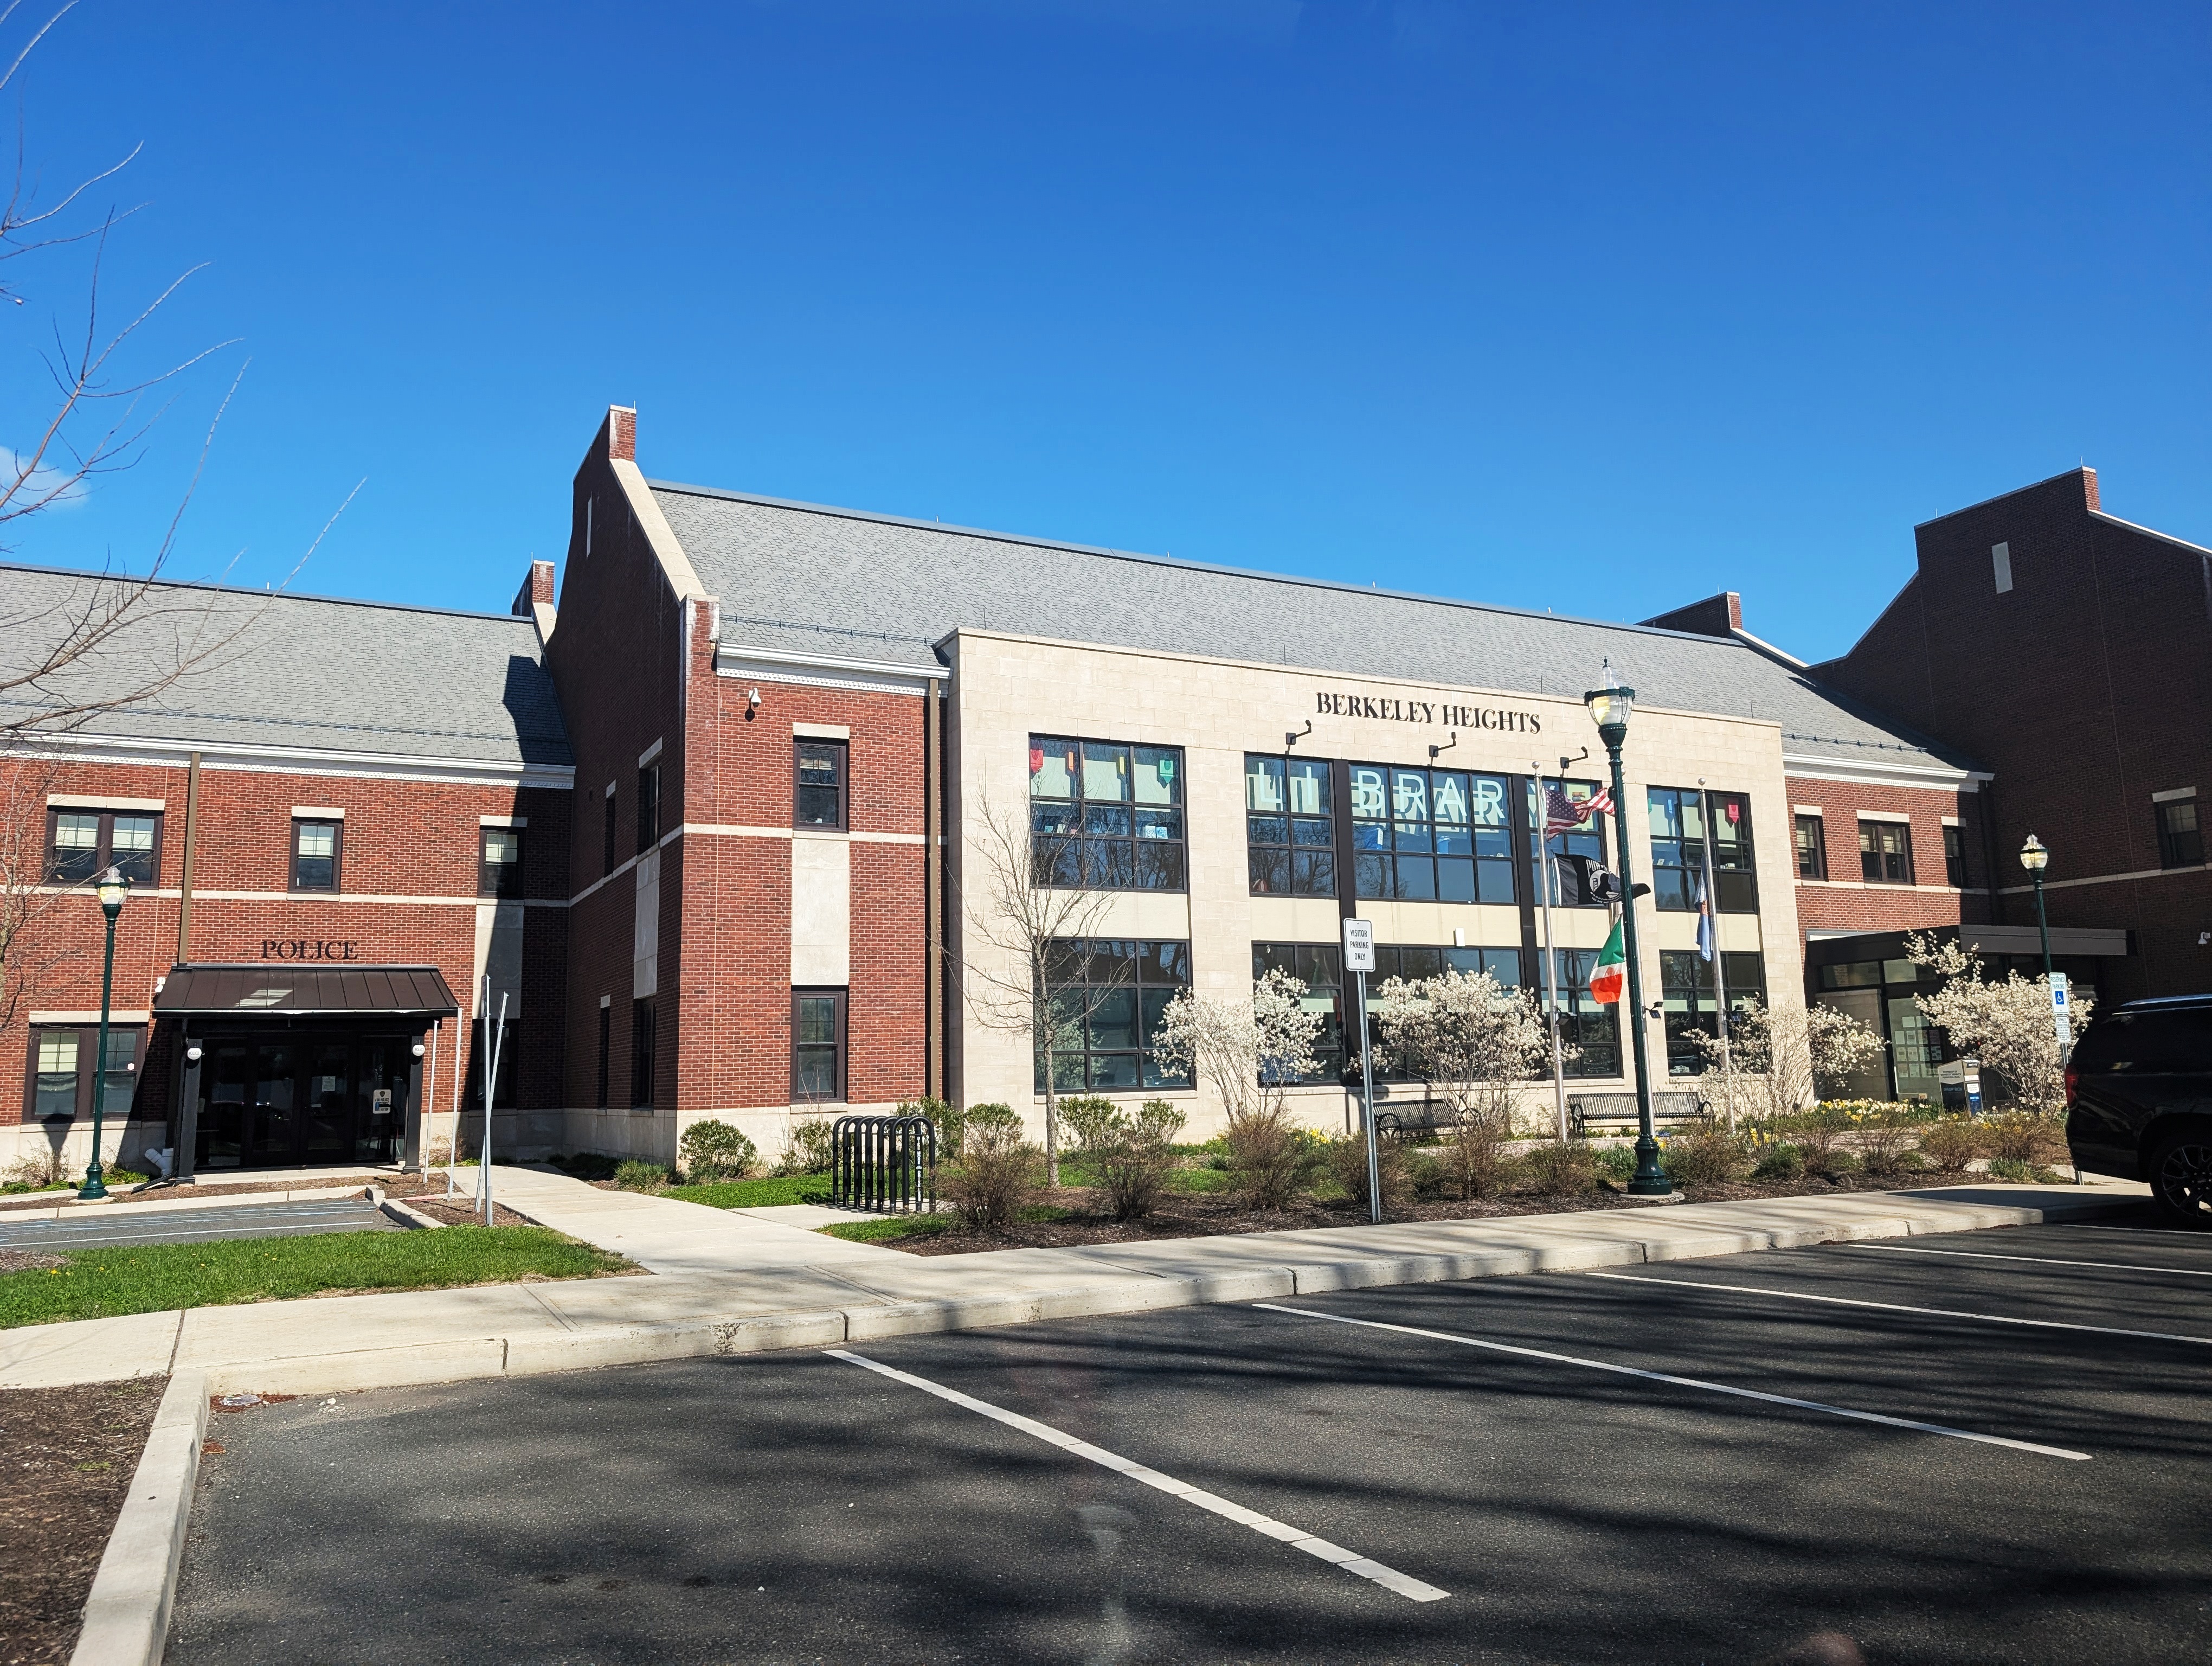
Berkeley Heights Township's auditors flagged the same three financial control problems for the second year in a row.
A corrective action plan for the township's 2025 annual audit is scheduled for a Township Council vote Tuesday, Oct. 6, as Resolution 2026-303. The plan, prepared by auditing firm Suplee, Clooney & Company, identifies failures in general ledger maintenance, purchasing procedures and payroll account reconciliation, as first reported by NJ21st.
All three findings also appeared in the 2024 corrective action plan. Receipt reconciliation problems stretch across all three audit years: 2023, 2024 and 2025.
Ledger problems still 'ongoing'
The 2025 plan states the general ledger was not maintained and reconciled with supporting records on time. The township's response blames the prior tax collector for failing to provide accurate monthly reports to the chief financial officer and says department receipts were not reconciled consistently with revenue accounts.
The township says the current tax collector now submits timely monthly reports and the CFO will perform monthly reconciliations. The corrective action is listed as "ongoing."
The 2024 plan attributed the same ledger failures to turnover in the CFO position and staffing shortages. NJ21st reported in October 2025 that the township had cycled through multiple CFOs under Mayor Angie Devanney's administration: a longtime CFO resigned in 2019, a second resigned in 2022, an interim followed, and a CFO hired in 2023 resigned in 2024.
Purchase orders issued after the fact
The second finding states the township did not maintain a complete system for setting aside money before purchases were made. Several purchase orders were processed as "confirming orders," meaning goods and services arrived before the paperwork was filed.
The township's fix: remind departments not to issue confirming orders.
That response is thinner than the 2024 plan, which called for the CFO to certify funding before purchases and contracts were placed on council agendas. The 2025 plan does not explain what happened to that earlier commitment. The 2024 plan also noted the purchasing problem had resulted in an "over expenditure" and that a prior-year contract was discovered with insufficient funds.
Payroll gaps persist
The third finding states individual payroll deduction accounts were not reconciled on time to identify and correct errors. The township says those accounts are now being reconciled "more regularly."
The 2024 plan had said payroll deductions were not tracked in an organized way in the township's software and that new procedures had been put in place. Those procedures did not prevent the same finding from reappearing.
Audit findings dropped from eight to three
The number of findings has decreased over the three years: eight items in the 2023 audit comments, seven in the 2024 corrective plan and three in the 2025 plan. The three that remain have persisted the longest.
The 2023 audit also flagged a bank reconciliation issue already marked as a prior-year recommendation. The 2024 plan revealed one escrow bank account had not been reconciled for years and that deposits were not always made within the required 48-hour window.
No on-record statement from Mayor Devanney, any council member or township staff addressing the repeat findings appears in public records as of Saturday, Oct. 3.
The Township Council meets Tuesday, Oct. 6. The agenda is posted on the township's website. Residents can attend or contact council members before the vote on Resolution 2026-303.